typical facility sizes
For many decades, asset-based lending (ABL) has been a reliable form of financing for middle-market companies across a wide range of situations and economic cycles.
The situations where Maple Bay’s approach makes the difference.
Middle market companies change lenders for many reasons. Some outgrow their current lender and need a larger, more flexible senior financing partner. Others find their credit profile has changed and they no longer fit their lender’s credit box. Either way, an asset-based structure can provide a fresh start built around the business as it is today.
Asset-based lending is well suited to seasonal businesses because borrowing availability often rapidly rises and falls with receivables and inventory. Seasonal advance rates can add capacity exactly when it’s needed most, even when inventory and receivables peak at different times of year.
Companies working through a challenging period often need more flexibility, patience, and sometimes additional capital. These periods often coincide with a need to restructure a broken capital structure.
For asset-intensive companies, an asset-based approach often provides the most senior debt in a change of control. In a new platform buyout, the senior debt structure is built on the target company’s assets and cash flow; in an add-on acquisition scenario the financing is based on the assets and cash flow of both companies.
When a division with meaningful working capital assets is carved out of a larger company, ABL can be an effective financing solution. Carve-outs often have limited stand-alone financial history, which can make cash flow lenders hesitant, while asset-based lending focuses on the performance of the collateral being acquired and the new vision.
Fast-growing companies often need a lender focused less on financial ratios and more on their expanding asset base. With ABL, borrowing capacity grows immediately as receivables and inventory grow, and new or used equipment needed for expansion can be financed as well.
Frequently, it is beneficial for a company to reassemble its balance sheet capital structure. This may include a borrower taking on additional senior debt to pay off sub- or seller-debt or even meet an earn-out obligation. It could also include taking on additional senior debt against a low leveraged asset base to pay a dividend to investors or pursue other strategic initiatives.
Expert in financing needs between $7.5 million and $35 million
Revolving Credit Facilities
Borrowing availability against accounts receivable and inventory that adjusts as the asset base grows, maximizing liquidity for working capital.
Equipment Term Loans
Term financing against existing machinery and equipment, based on appraisals by qualified third-party industry experts.
Real Estate Term Loans
Term financing against the appraised fair market value of owner-occupied real estate used in operations.
Capital Expenditure Facilities
A committed line to finance planned equipment purchases after closing, for new or high-quality used equipment. Used equipment may require an appraisal.
Cash Flow Term Loans
For consistently profitable, growing, well-capitalized companies, term debt beyond collateral values may be available on a select basis. These loans require a substantial asset base and accompany a revolving credit facility as the primary financing need.
Stand-Alone Term Loans
Term loans of $10 million or more without a revolving facility, considered case by case based on the appraised value of fixed assets, sometimes in partnership with other capital providers.
Complementary Capital and Introductions
Every financing is unique. When a deal needs more than senior debt, such as specialized or FMV equipment leasing, second lien, mezzanine, or equity, Maple Bay draws on long-standing relationships with capital providers across the middle market. And when another lender is the better fit, we’re glad to make the introduction.
Every situation is unique and the middle market is very dynamic.
Below are some general guidelines, but it’s always most valuable to simply have a conversation. Candor is a core belief, and communicating how, when and whether a transaction can be completed is highly valued.
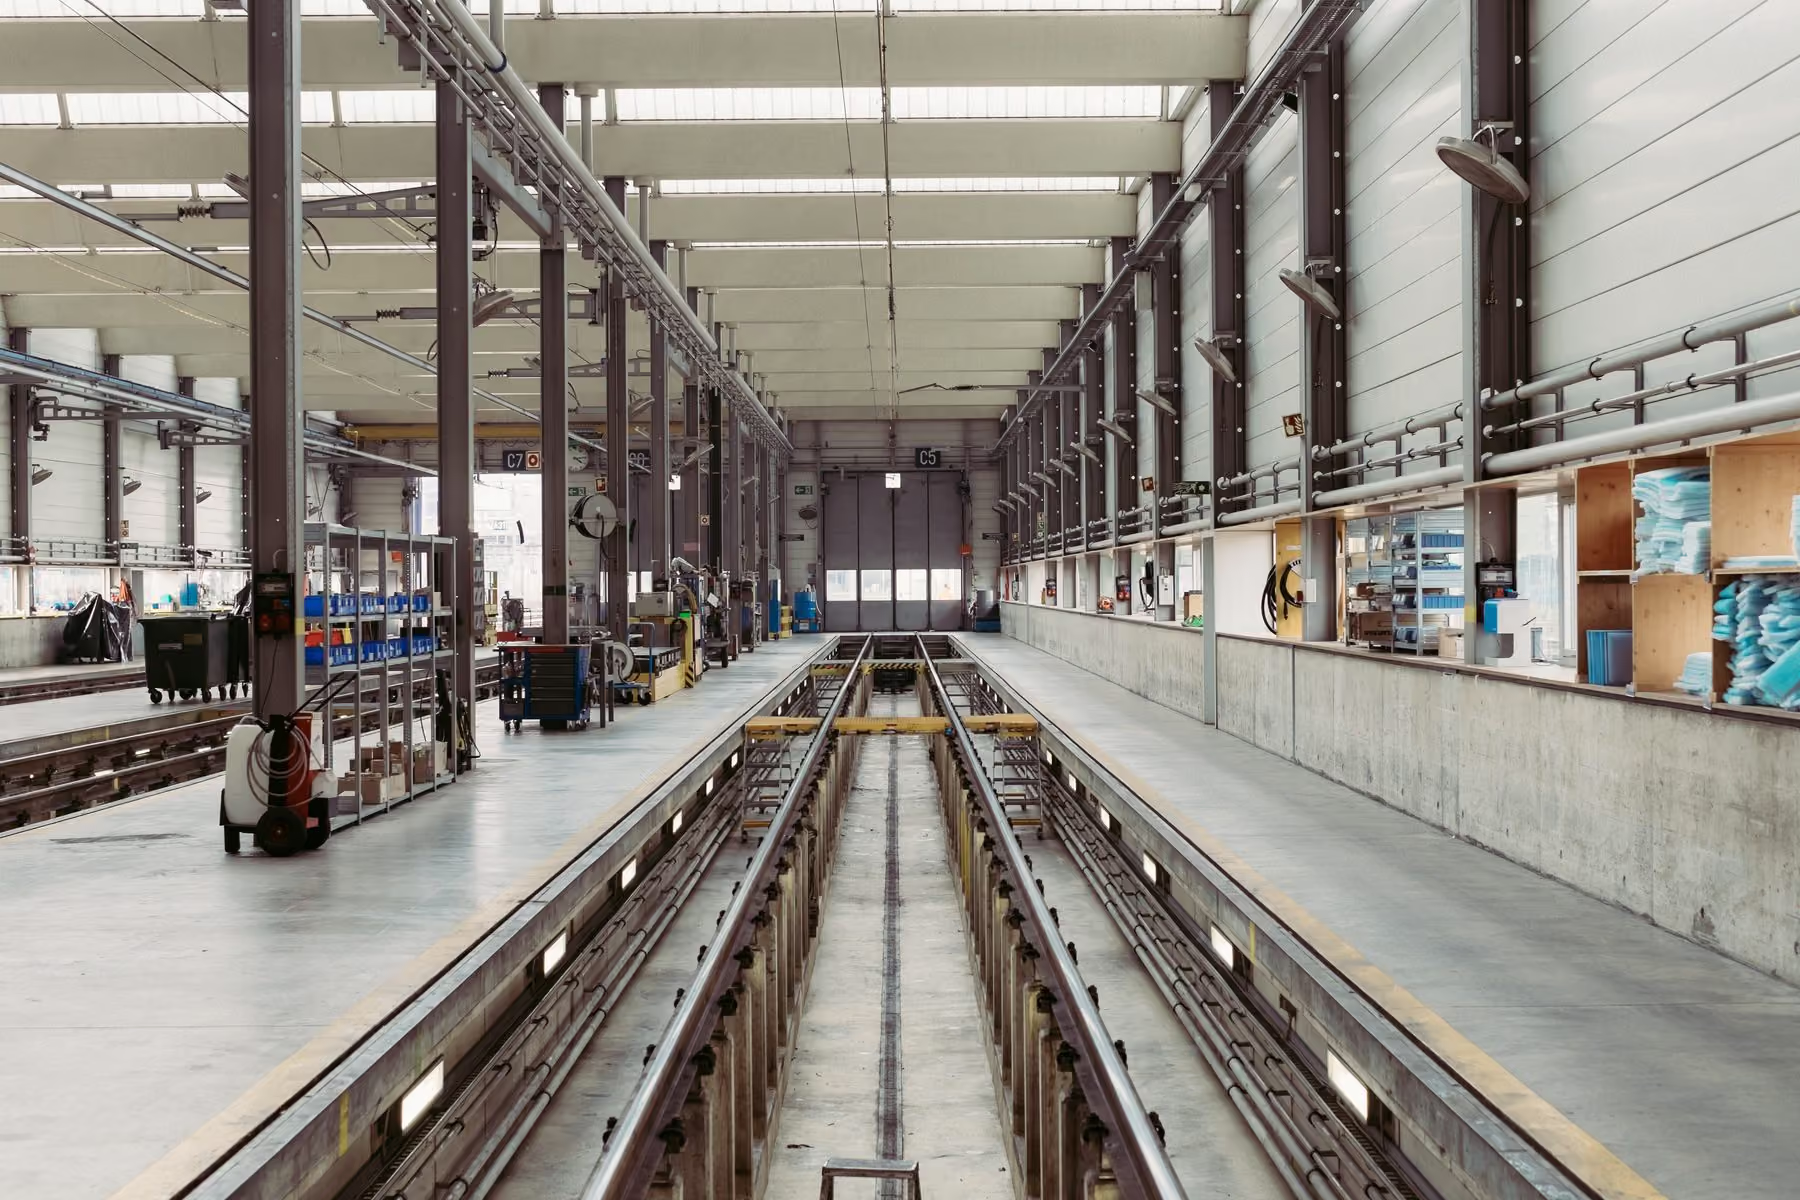
Industry agnostic
Industry agnostic with our primary value proposition geared toward working capital intense manufacturers and distributors with sales generally between $25 million and $150 million.
Following our national-base of valued referral sources from our home base of Chicago
Each middle market borrower has its own unique story and every deal starts with a conversation. Below are high level guidelines around Maple Bay performance parameters
Traditional covenant packages are not necessary, and structures can be tailored to the borrower’s situation.
Turnarounds need a strong plan to return to profitability that can be documented through due diligence.
Cash Flow loans require consistent profitability, satisfactory proforma cash flow coverage, strong capital structures, and are mostly sponsor backed.
Clear communication throughout the process
Initial conversation
We get to know your business: its history, current situation, needs, and outlook. This helps us quickly determine whether we’re a good fit.
Information review
We request financial and collateral information and complete a preliminary analysis to determine whether, how, and when a financing could come together.
Discuss the approach
Before seeking approval, we walk you through our proposed structure, so there are no surprises and your input is reflected.
Prescreen and proposal
Once the structure is preliminarily approved, we issue a proposal outlining terms, conditions, and next steps.
Due diligence
After the proposal is signed and a diligence deposit is received, we engage third-party field exam and appraisal firms and complete our review and pursue formal approval.
Documentation, closing, and beyond
We work with counsel to finalize documentation and close. After closing, we’re constantly engaged as your business evolves.
Committed to the Lower Segment of the Middle Market
There are roughly 200,000 companies in the US economy with between $10 million and $1 billion in revenue1 and a large and important share of these companies are in Maple Bay’s target revenue range of $25 million to $150 million. Often, companies of this size are not only the borrowers with the most specialized needs but also frequently overlooked by the broad universe of lenders. Fortunately, this is a niche the Maple Bay team knows well and is committed to serving with tailored ABL solutions.
Further, borrowers are also often best served by a lender focused on companies their size, rather than being that lender’s largest or smallest relationship. We’d welcome the conversation.
1 Source: S&P Capital IQ: Commercially-active businesses in the U.S. All subsidiary and business establishment data are combined. Additionally, public sector entities are excluded. As of 1/29/24.
Illustrative only. Lender focus areas are approximate and do not reflect firm cutoffs by revenue, facility size, or credit profile.